Mortgage Rates Are Rising Again: 6 Ways Homebuyers Can Explore Lower Mortgage Payments
With mortgage rates climbing again, buying a home in Orange County can feel more challenging. Higher borrowing costs affect monthly payments, purchasing power, and how much home buyers can comfortably afford. But a higher market rate does not mean every buyer has the same financing options.
From mortgage rate buydowns and assumable loans to seller concessions and first-time homebuyer programs, there are several strategies worth exploring before putting your homeownership plans on hold.
The key is having the right real estate agent and mortgage lender working together to help you understand your options, compare the numbers, and negotiate a financing strategy that fits your goals!
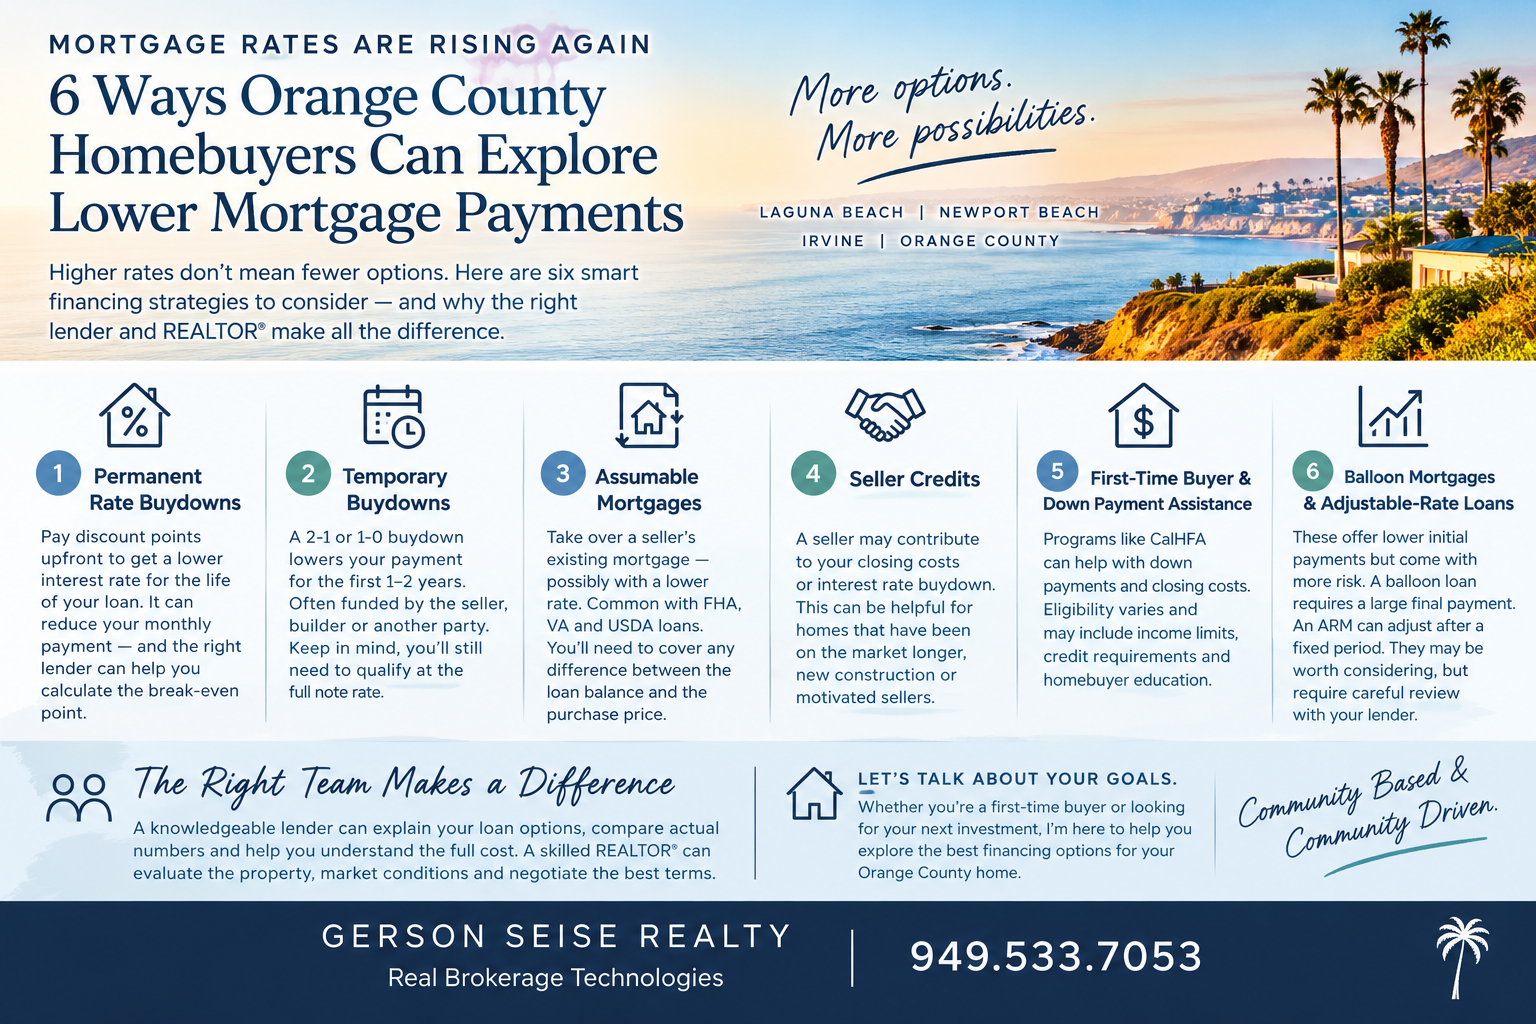
1. Permanent Mortgage Rate Buydowns
A permanent rate buydown allows a buyer to pay discount points upfront in exchange for a lower mortgage interest rate over the life of the loan. One discount point generally costs 1% of the loan amount, although the actual rate reduction varies by lender and market conditions.
For example, a buyer purchasing a home in Laguna Beach, Newport Beach, Irvine, or elsewhere in Orange County might compare paying upfront to secure a lower rate against keeping that money available for closing costs, reserves, or improvements.
The important question is whether the monthly savings justify the upfront expense. Your lender can calculate the break-even point, which is how long you need to keep the mortgage for the savings to outweigh the cost.
2. Temporary Rate Buydowns: The 2-1 and 1-0 Options
A temporary mortgage rate buydown reduces the buyer's effective payment for an initial period, usually with funds contributed by the seller, builder, or another permitted party.
Two common options include:
2-1 buydown: The effective rate is 2 percentage points below the note rate in year one, 1 percentage point below in year two, then returns to the full note rate.
1-0 buydown: The effective rate is 1 percentage point below the note rate during the first year before returning to the full note rate.
These options can help buyers manage their initial housing costs, particularly when negotiating with a seller who is willing to contribute toward closing costs.
However, the lower initial payment is temporary. Buyers generally must qualify based on the full contractual rate, subject to the applicable loan program's requirements. Make sure the payment at the full rate remains affordable.
3. Assume an Existing Mortgage With a Lower Interest Rate
An assumable mortgage allows an eligible buyer to take over a seller's existing mortgage under its original terms, subject to lender or servicer approval and the loan's requirements.
This can be particularly attractive when a seller has an older mortgage with an interest rate significantly below current market rates. Certain FHA, VA, and USDA loans may be assumable.
There is one important catch: the existing mortgage balance may be much lower than the home's purchase price. Buyers must determine how to cover the difference, potentially through a substantial down payment or additional financing.
For example, if a home sells for $900,000 and the assumable mortgage balance is $500,000, the buyer must find a way to cover the remaining $400,000, plus applicable transaction costs. The figures are illustrative, not a current Orange County listing or loan offer.
An assumption can offer meaningful savings, but the process can take time. Buyers should have a lender evaluate the financing gap and confirm the loan's eligibility before making assumptions about affordability.
4. Negotiate Seller Credits Instead of Focusing Only on Price
In Southern California, the right offer involves more than the purchase price. Depending on the property's circumstances, a seller may be willing to contribute toward eligible closing costs or an interest rate buydown.
This can be especially worth exploring for homes that have been on the market longer, listings with price reductions, new construction, or sellers who prioritize a smooth and timely closing.
A knowledgeable REALTOR® can help assess the property's market position, identify potential negotiating opportunities, and structure an offer that considers price, seller credits, repairs, and other terms.
Seller contributions are subject to loan program limits, lender rules, and the negotiated contract. A seller credit also cannot necessarily be used for every expense or converted into cash back to the buyer.
5. Explore First-Time Homebuyer and Down Payment Assistance Programs
Buyers should not overlook assistance programs simply because mortgage rates are elevated. Eligible buyers may be able to access down payment or closing cost assistance through state, local, or other qualifying programs.
California's Housing Finance Agency, commonly known as CalHFA, offers home financing programs with eligibility requirements that can include income limits, credit qualifications, homebuyer education, and occupancy rules. Program availability and terms can change.
For first-time buyers in Orange County, ask a participating lender to compare available programs with a standard conventional, FHA, or other eligible mortgage. Assistance can help preserve savings, although it may involve a second loan, repayment requirements, or other costs.
The lowest advertised rate is not automatically the best overall deal. Compare the total monthly payment, upfront cash needed, mortgage insurance, and long-term obligations.
6. What About Balloon Mortgages and Adjustable-Rate Loans?
Some buyers encounter financing options that offer lower initial payments but introduce additional risks.
A balloon mortgage typically requires a large final payment after a shorter loan term. Refinancing may be possible, but it is not guaranteed. If property values fall, lending requirements change, or your financial circumstances worsen, refinancing may become difficult. A balloon loan should never be chosen based solely on its initial payment.
An adjustable-rate mortgage (ARM) generally begins with a fixed-rate period before the interest rate can adjust under the loan's terms. An ARM may be worth comparing if you understand the adjustment schedule, payment caps, and potential future increases. Do not assume you will be able to refinance before the rate changes.
These products are not the same as a permanent rate buydown. They change how interest or repayment works and should be evaluated carefully with a qualified lender.
Why the Right REALTOR® and Mortgage Lender Matter
Mortgage financing is not one-size-fits-all. A lender can explain loan eligibility, interest rates, points, monthly payments, closing costs, and qualification requirements. A REALTOR® can help evaluate the property, local market conditions, seller motivation, and opportunities to negotiate financing concessions.
Working together, these professionals can help you compare options using actual loan estimates rather than relying on advertised rates or general advice online.
Before deciding, ask your lender to compare at least two or three financing scenarios, including the upfront costs, full monthly payment, break-even point, and long-term risks. Your REALTOR® can then help determine whether the purchase terms and seller concessions are realistic for that particular property.
The Bottom Line for Orange County Homebuyers
Rising mortgage rates make preparation and smart negotiation more important, not less! A permanent buydown, temporary buydown, assumable mortgage, seller credit, or eligible assistance program may help, but the best option depends on your finances, the property, and how long you plan to own the home.
You do not need to figure everything out alone. If you are considering buying in Laguna Beach, Newport Beach, Irvine, or elsewhere in Orange County, let's talk through your goals and connect the right financing questions with the right professionals.
-Gerson
Written by Gerson Seise REALTOR® Cell: 949.533.7053
GERSON SEISE REALTY - Real Brokerage Technologies
Recent Posts